Gap
High-Selectivity
Trades the weekly gap between Friday close and Sunday open — gap-fill and gap-rejection setups. Low-frequency, high-conviction entries across MNQ, MGC, NAS and XAU. Total +$86,755 across all tracks at 100K presets (Apr 2025 – Sep 2026): modeled +$56,567, live +$30,188; best PF 4.84 (NAS).
At a glance
4.84 best PF (NAS) · 55.6% best WR (MNQ)
Best-performing instrument per metric (max 3 from one instrument), total Apr 2025 – Sep 2026 at the 100K preset; modeled and live layers per instrument below. Forecast metrics: Monte Carlo, 1,500 paths, 3-year horizon, input Apr 2025 – Sep 2026. Viability 3y = % of MC paths that never hit the hard drawdown. Payout potential : blow = full payout units reached in profit per one account blow over 3y (potential, not a payout schedule). TTP = median days to first payout unit.
Take Gap’s numbers with you.
The Playbook puts Gap next to every other strategy and portfolio in the catalogue, modeled and live shown separately, with the preset for each account tier. One PDF, then our letters with what the systems did.
By email, from Puerto Viejo, Costa Rica. Unsubscribe anytime.
100K FP preset (8 ct) · standalone
4.81 PF · 52.4% Win rate · $1,768 Max DD (EOD) · 1.66 Sharpe
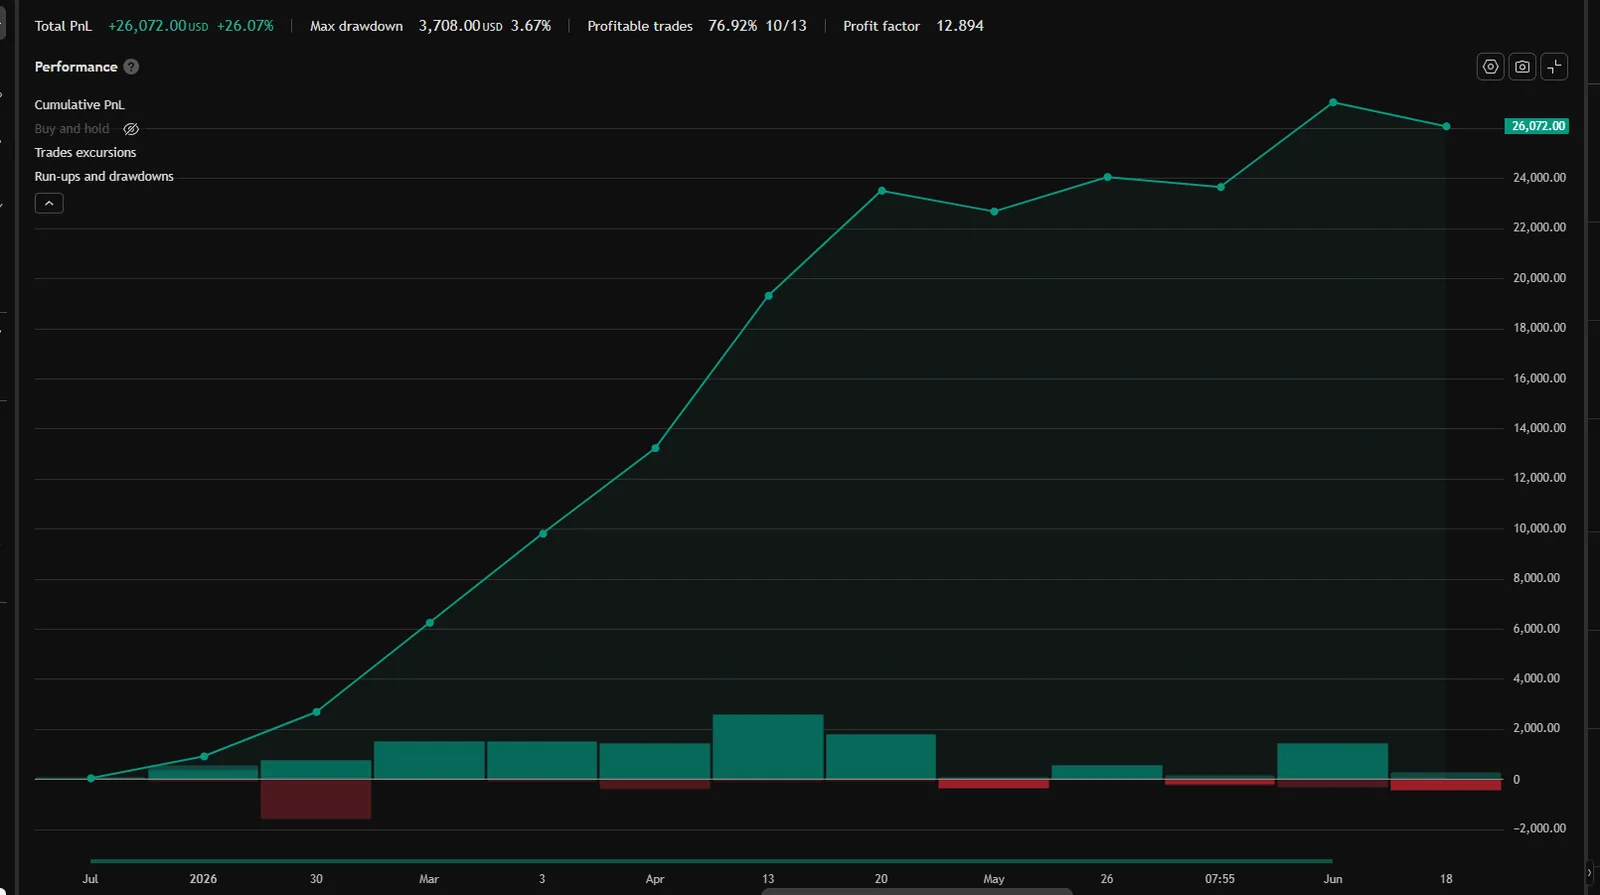
Equity curve · modeled + live
Daily P&L applied to the $100,000 starting balance at the 100K FP preset (8 ct), log scale. Gray = modeled (2025-04-01 → 2026-03-31); accent = live (2026-04-01 → 2026-09-30), right of the “LIVE →” marker.
Modeled 12 months (Apr 2025 – Mar 2026) · detail
Quarterly breakdown · modeled Q2'25–Q1'26, live since Q2'26
| Quarter | Layer | Net | WR | Trades | Max DD (EOD) |
|---|---|---|---|---|---|
| Q2'25 | modeled | −$1,768 | 0.0% | 4 | $1,768 |
| Q3'25 | modeled | +$32 | 100.0% | 1 | $0 |
| Q4'25 | modeled | +$0 | — | 0 | $0 |
| Q1'26 | modeled | +$9,768 | 100.0% | 4 | $0 |
| Q2'26 live | live | +$16,272 | 62.5% | 8 | $960 |
| Q3'26 live | live | −$536 | 25.0% | 4 | $1,536 |
Drawdowns are EOD basis; intrabar peak-to-trough runs higher. Live quarters are real-account results at the same preset.
Stats · modeled and live, separately
| Layer | Avg win / loss | W:L | Largest win / loss | Max DD EOD | Sharpe | Sortino | Calmar | Avg bars |
|---|---|---|---|---|---|---|---|---|
| Modeled Apr 2025 – Mar 2026 | $1,960 / −$442 | 4.43 | $3,560 / −$616 | $1,768 (1.77%) | 1.34 | 6.84 | 4.54 | 13.1 |
| Live Apr 2026 – Sep 2026 | $3,367 / −$744 | 4.53 | $6,088 / −$960 | $1,696 (1.70%) | 2.20 | 11.05 | 18.56 | 37.8 |
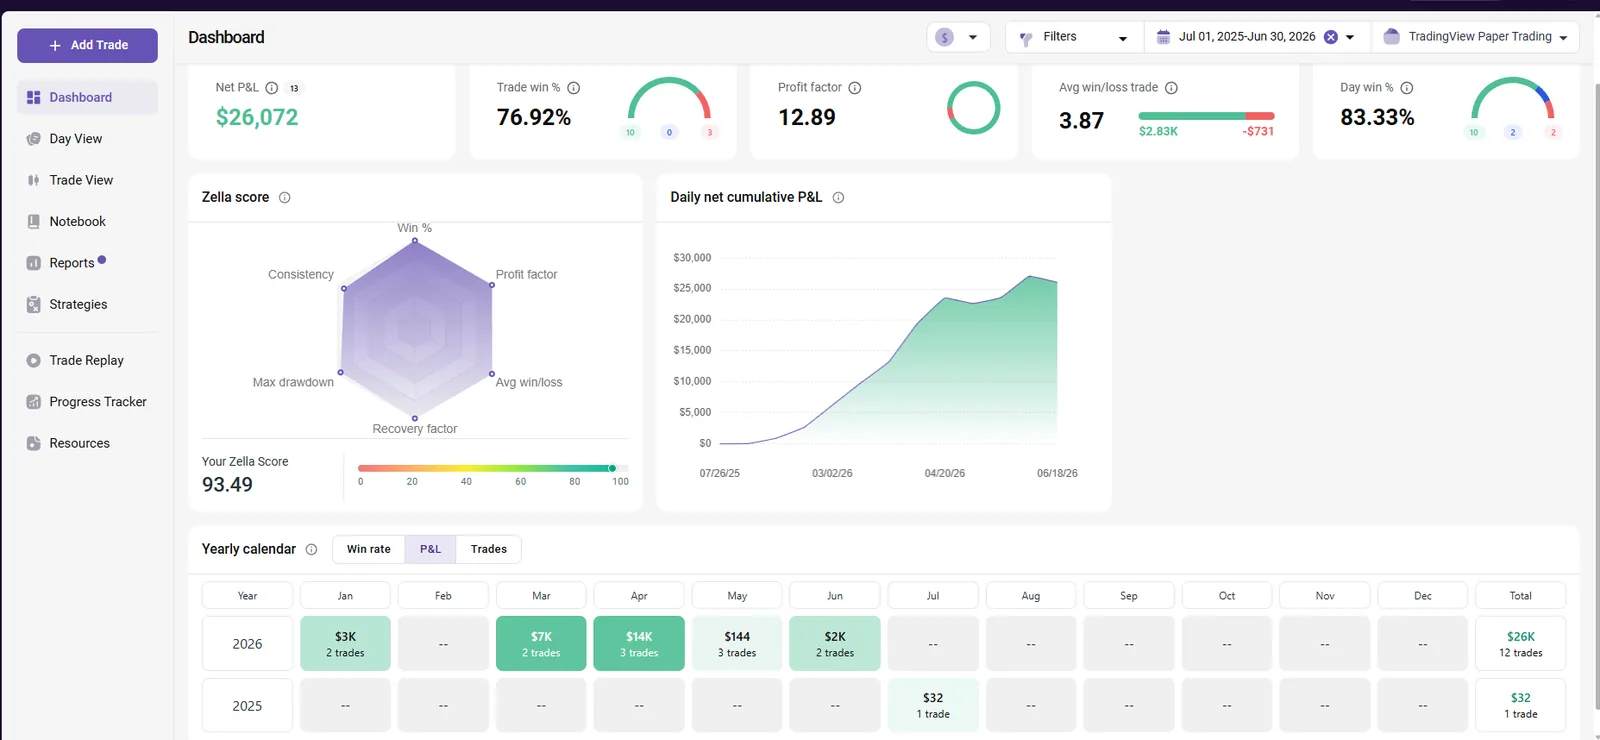
TradeZella merges partial exits into one position, so its trade count runs below the TradingView trade list; net P&L matches to the dollar.
Account sizing · Monte Carlo 1,500 paths × 3y
| Account | Qty | Blow/y | Net/y P50 (MC) | Median TTP | Status |
|---|---|---|---|---|---|
| 50K FP | 6 ct | 2.62% | $8,607 | 83d | SAFE |
| 100K FP | 8 ct | 2.04% | $11,476 | 118d | SAFE |
| 150K FP | 10 ct | 1.17% | $14,344 | 145d | SAFE |
Monte Carlo, 1,500 paths, 3-year horizon, input Apr 2025 – Sep 2026. Forecast layer, separate from modeled and live results above. Drawdown floor: end-of-day trailing.
100K FP preset (5 ct) · standalone
4.05 PF · 55.6% Win rate · $3,140 Max DD (EOD) · 1.81 Sharpe
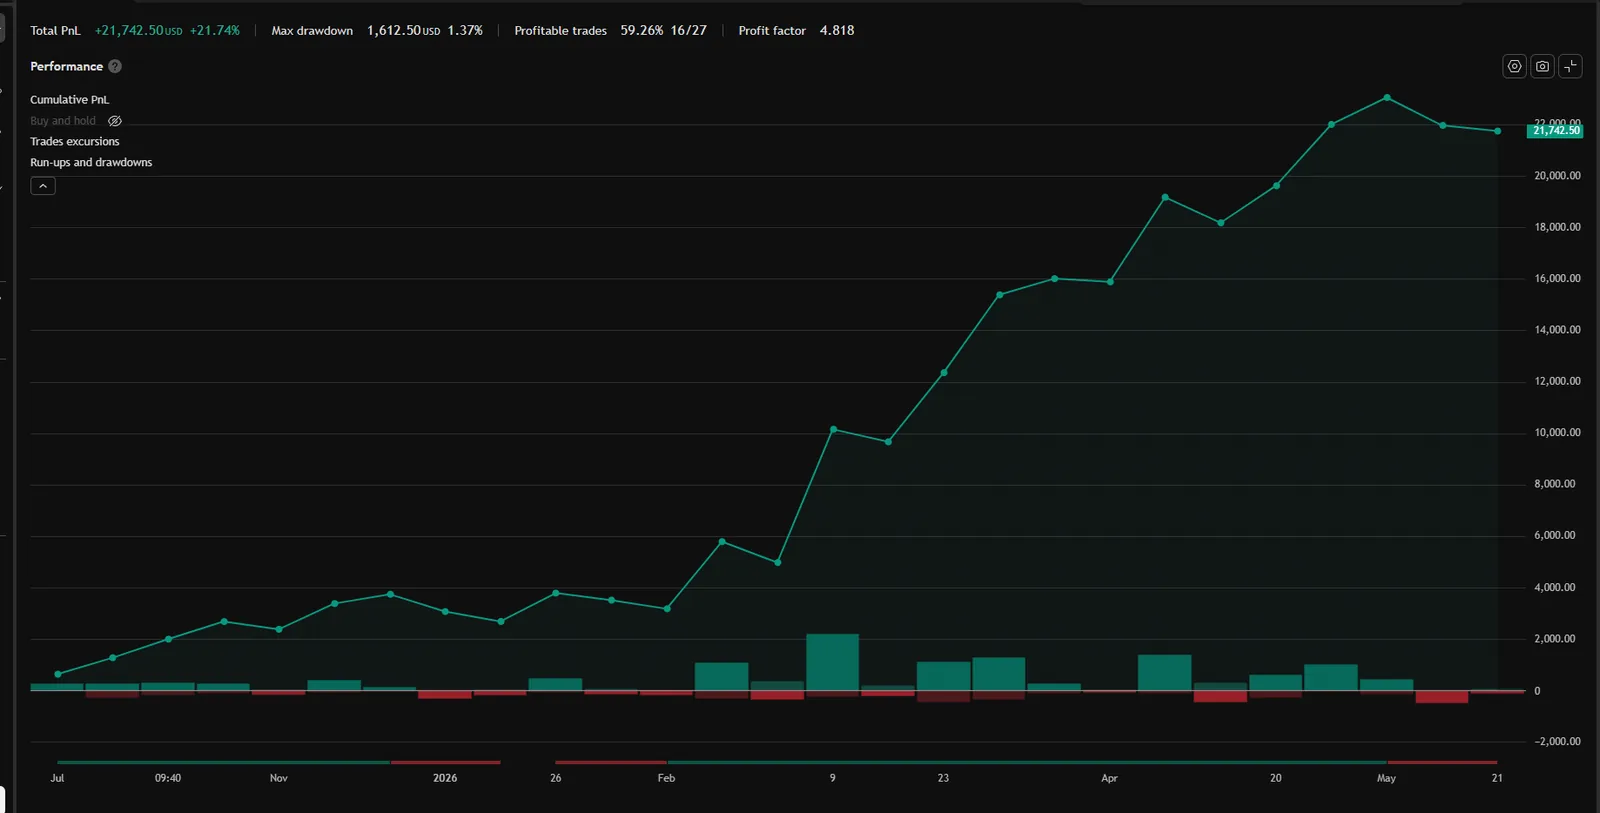
Equity curve · modeled + live
Daily P&L applied to the $100,000 starting balance at the 100K FP preset (5 ct), log scale. Gray = modeled (2025-04-01 → 2026-03-31); accent = live (2026-04-01 → 2026-09-30), right of the “LIVE →” marker.
Modeled 12 months (Apr 2025 – Mar 2026) · detail
Quarterly breakdown · modeled Q2'25–Q1'26, live since Q2'26
| Quarter | Layer | Net | WR | Trades | Max DD (EOD) |
|---|---|---|---|---|---|
| Q2'25 | modeled | +$11,180 | 60.0% | 10 | $2,228 |
| Q3'25 | modeled | +$2,508 | 100.0% | 4 | $0 |
| Q4'25 | modeled | +$1,062 | 66.7% | 3 | $300 |
| Q1'26 | modeled | +$12,188 | 50.0% | 12 | $1,135 |
| Q2'26 live | live | +$5,650 | 50.0% | 8 | $1,390 |
| Q3'26 live | live | +$2,515 | 37.5% | 8 | $1,750 |
Drawdowns are EOD basis; intrabar peak-to-trough runs higher. Live quarters are real-account results at the same preset.
Stats · modeled and live, separately
| Layer | Avg win / loss | W:L | Largest win / loss | Max DD EOD | Sharpe | Sortino | Calmar | Avg bars |
|---|---|---|---|---|---|---|---|---|
| Modeled Apr 2025 – Mar 2026 | $1,844 / −$569 | 3.24 | $6,728 / −$1,050 | $2,228 (2.23%) | 1.88 | 14.82 | 12.09 | 33.5 |
| Live Apr 2026 – Sep 2026 | $1,919 / −$585 | 3.28 | $3,290 / −$1,170 | $3,140 (3.14%) | 1.73 | 5.28 | 5.20 | 49.5 |
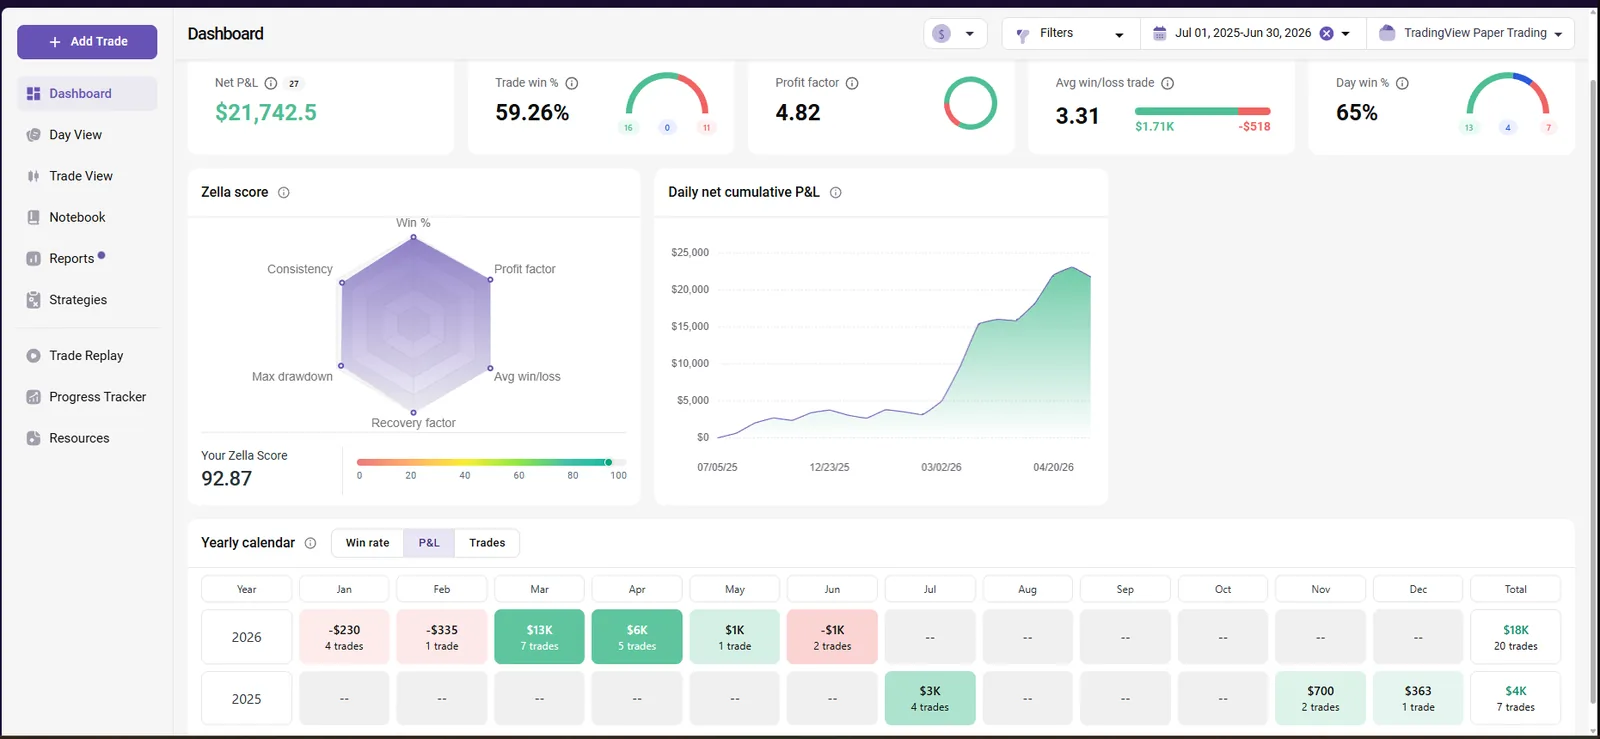
TradeZella merges partial exits into one position, so its trade count runs below the TradingView trade list; net P&L matches to the dollar.
Account sizing · Monte Carlo 1,500 paths × 3y
| Account | Qty | Blow/y | Net/y P50 (MC) | Median TTP | Status |
|---|---|---|---|---|---|
| 50K FP | 3 ct | 1.40% | $9,424 | 72d | SAFE |
| 100K FP | 5 ct | 1.76% | $15,707 | 84d | SAFE |
| 150K FP | 8 ct | 2.18% | $25,132 | 79d | SAFE |
Monte Carlo, 1,500 paths, 3-year horizon, input Apr 2025 – Sep 2026. Forecast layer, separate from modeled and live results above. Drawdown floor: end-of-day trailing.
100K Swing preset (8 lot) · standalone
4.84 PF · 50.0% Win rate · $934 Max DD (EOD) · 1.65 Sharpe
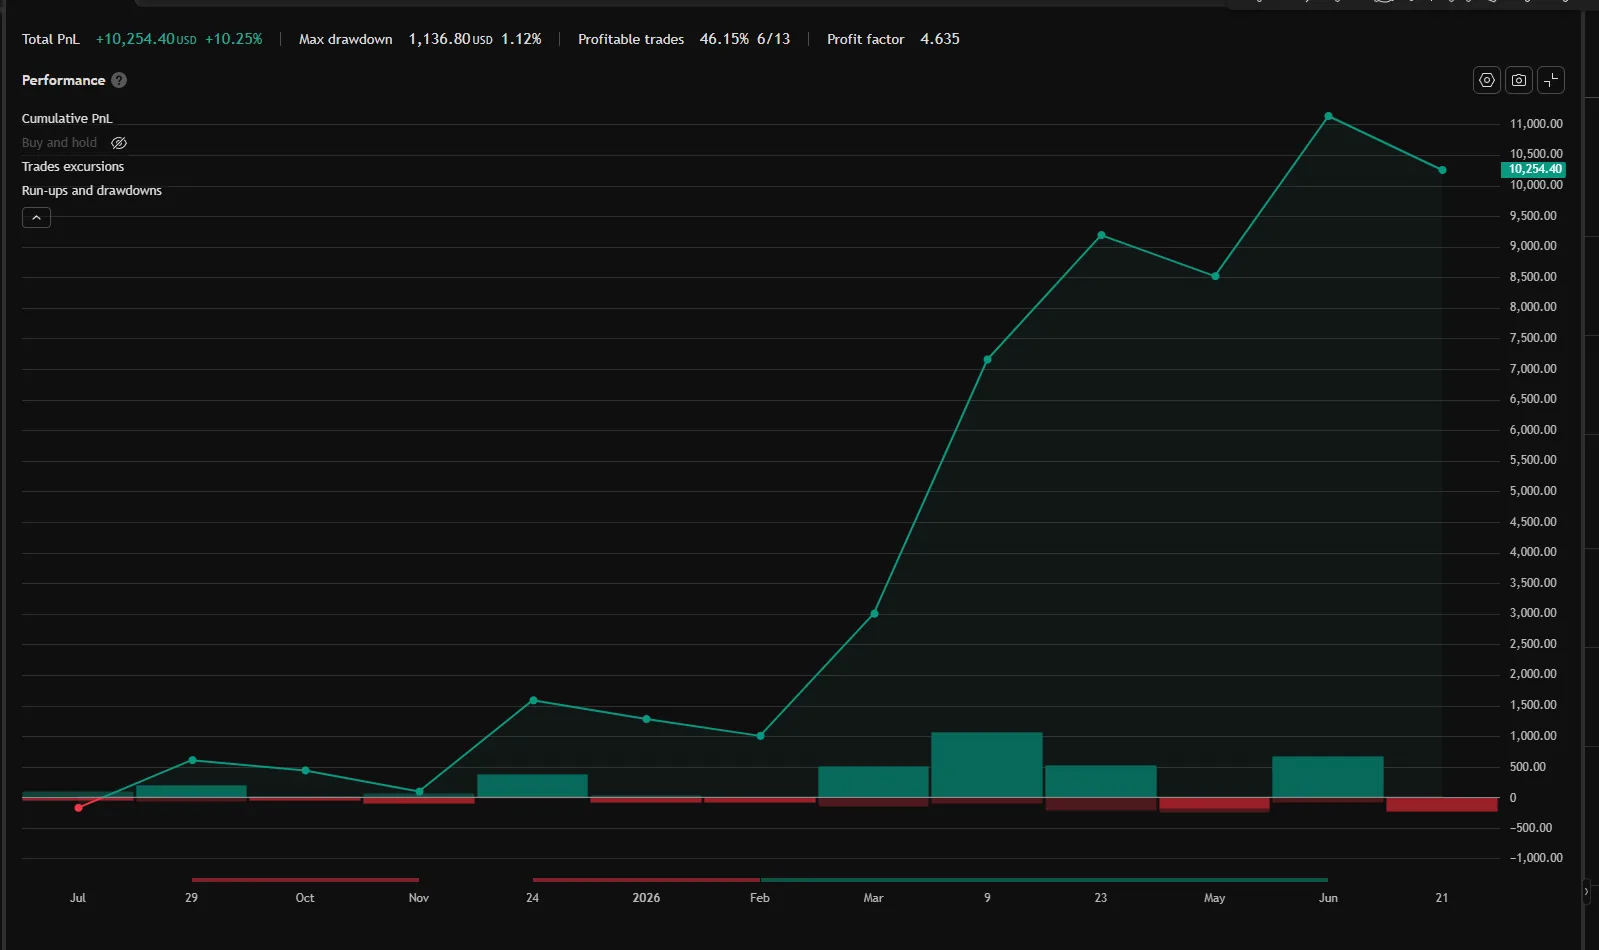
Equity curve · modeled + live
Daily P&L applied to the $100,000 starting balance at the 100K Swing preset (8 lot), log scale. Gray = modeled (2025-04-01 → 2026-03-31); accent = live (2026-04-01 → 2026-09-30), right of the “LIVE →” marker.
Modeled 12 months (Apr 2025 – Mar 2026) · detail
Quarterly breakdown · modeled Q2'25–Q1'26, live since Q2'26
| Quarter | Layer | Net | WR | Trades | Max DD (EOD) |
|---|---|---|---|---|---|
| Q2'25 | modeled | +$7,107 | 66.7% | 3 | $616 |
| Q3'25 | modeled | +$589 | 50.0% | 2 | $181 |
| Q4'25 | modeled | +$949 | 33.3% | 3 | $534 |
| Q1'26 | modeled | +$7,520 | 60.0% | 5 | $638 |
| Q2'26 live | live | +$990 | 33.3% | 3 | $934 |
| Q3'26 live | live | +$2,212 | 50.0% | 6 | $760 |
Drawdowns are EOD basis; intrabar peak-to-trough runs higher. Live quarters are real-account results at the same preset.
Stats · modeled and live, separately
| Layer | Avg win / loss | W:L | Largest win / loss | Max DD EOD | Sharpe | Sortino | Calmar | Avg bars |
|---|---|---|---|---|---|---|---|---|
| Modeled Apr 2025 – Mar 2026 | $2,590 / −$328 | 7.90 | $5,244 / −$616 | $797 (0.80%) | 1.89 | 16.82 | 20.28 | 72.9 |
| Live Apr 2026 – Sep 2026 | $1,568 / −$614 | 2.55 | $2,606 / −$934 | $934 (0.93%) | 1.06 | 2.75 | 6.85 | 14.0 |
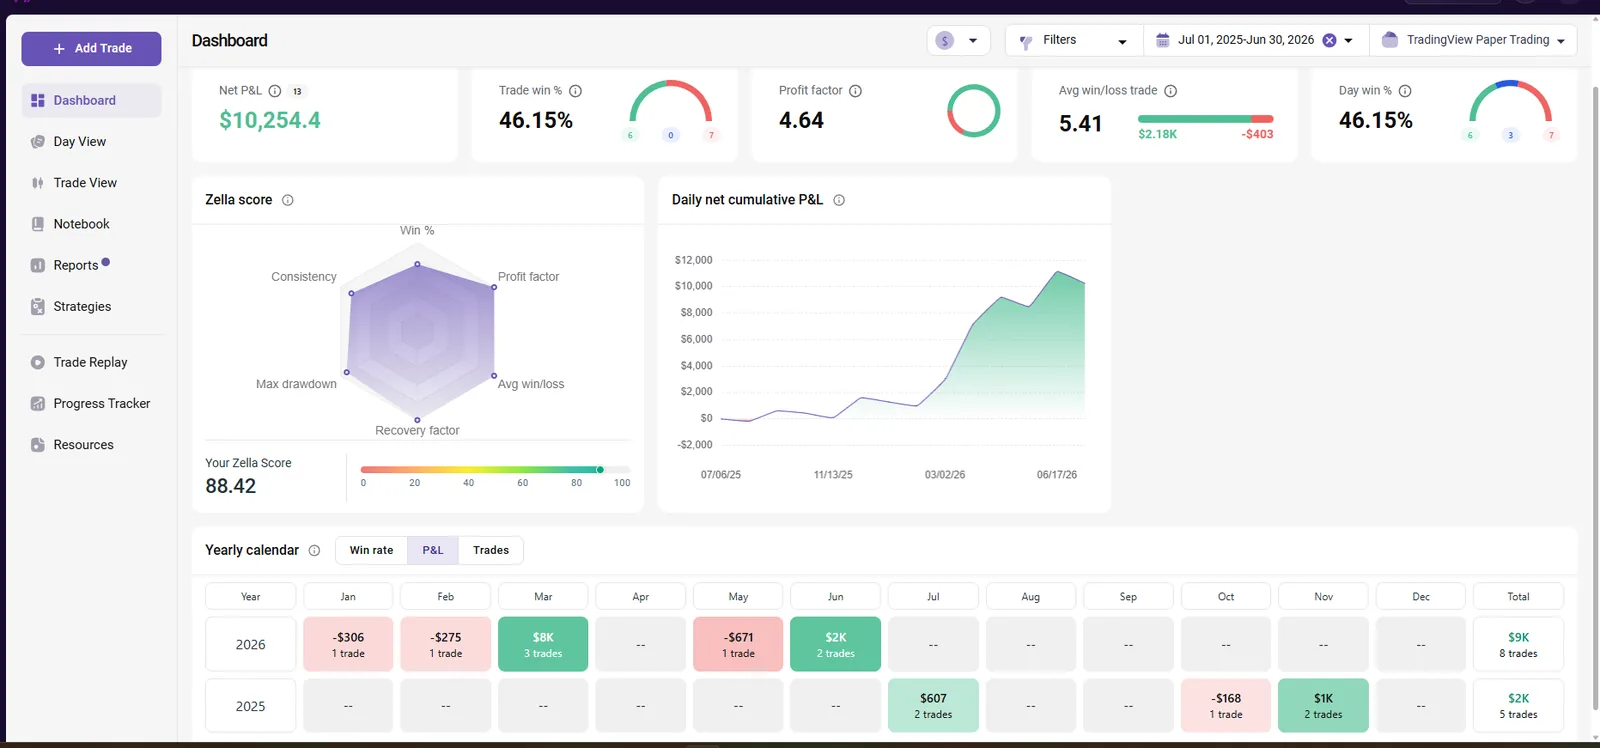
TradeZella merges partial exits into one position, so its trade count runs below the TradingView trade list; net P&L matches to the dollar.
Account sizing · Monte Carlo 1,500 paths × 3y
| Account | Qty | Blow/y | Net/y P50 (MC) | Median TTP | Status |
|---|---|---|---|---|---|
| 50K Swing | 4 lot | 0.00% | $4,659 | 237d | SAFE |
| 100K Swing | 8 lot | 0.00% | $9,318 | 237d | SAFE |
| 200K Swing | 16 lot | 0.00% | $18,636 | 237d | SAFE |
Monte Carlo, 1,500 paths, 3-year horizon, input Apr 2025 – Sep 2026. Forecast layer, separate from modeled and live results above. Drawdown floor: static; swing account, positions may be held overnight.
100K Swing preset (0.30 lot) · portfolio-only
2.78 PF · 42.9% Win rate · $1,770 Max DD (EOD) · 1.44 Sharpe
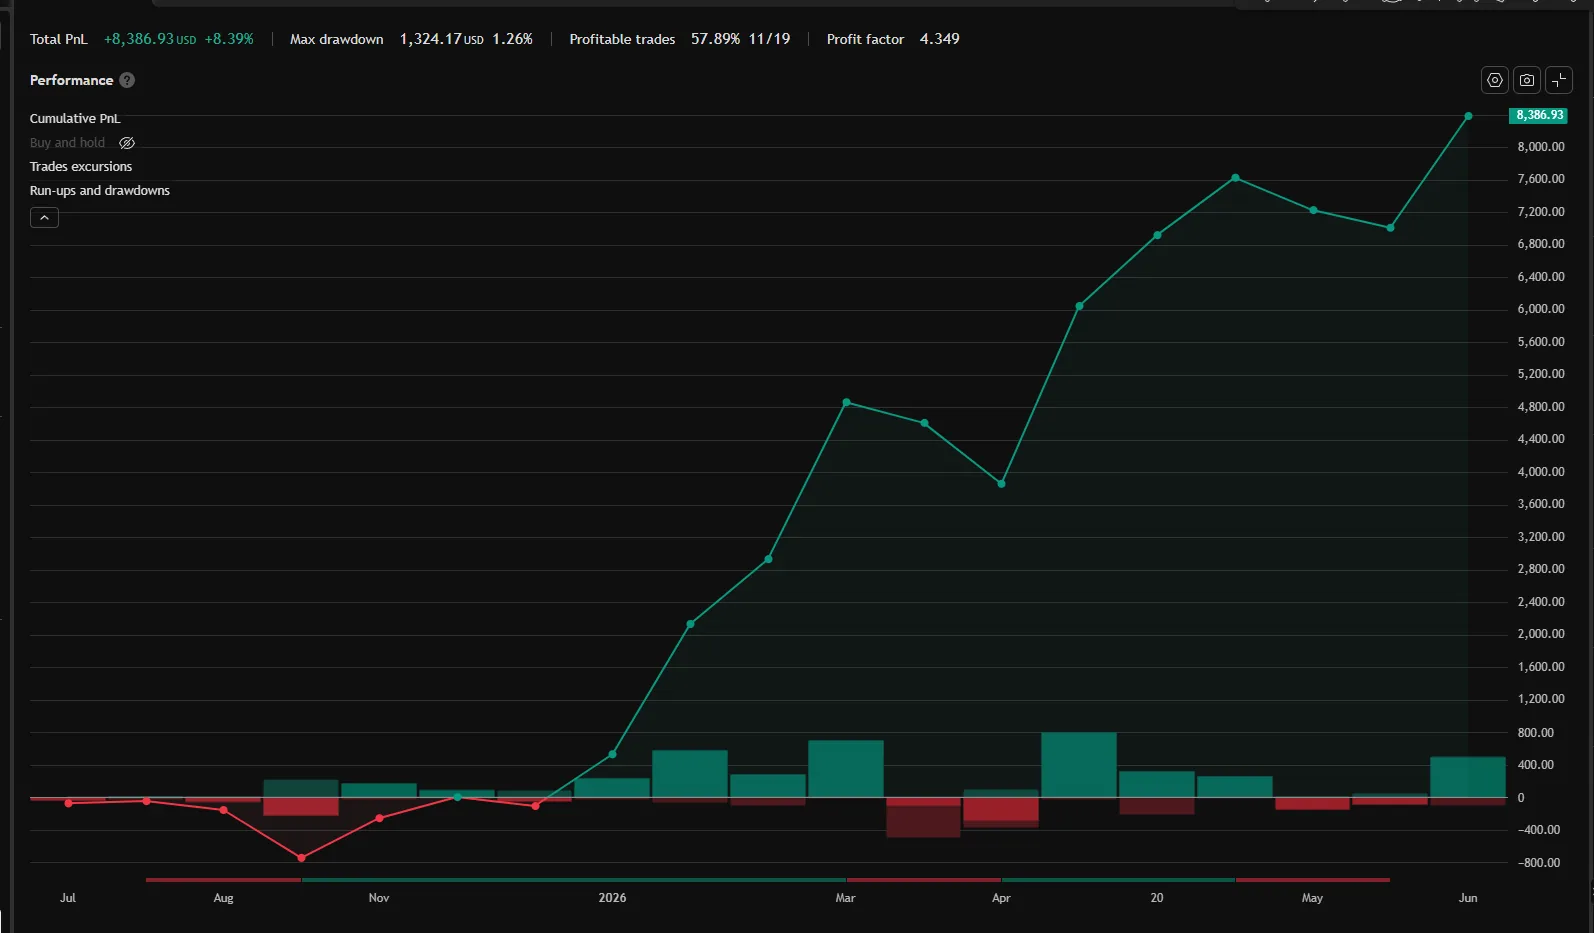
Equity curve · modeled + live
Daily P&L applied to the $100,000 starting balance at the 100K Swing preset (0.30 lot), log scale. Gray = modeled (2025-04-01 → 2026-03-31); accent = live (2026-04-01 → 2026-09-30), right of the “LIVE →” marker.
Modeled 12 months (Apr 2025 – Mar 2026) · detail
Quarterly breakdown · modeled Q2'25–Q1'26, live since Q2'26
| Quarter | Layer | Net | WR | Trades | Max DD (EOD) |
|---|---|---|---|---|---|
| Q2'25 | modeled | +$824 | 33.3% | 9 | $1,024 |
| Q3'25 | modeled | −$156 | 33.3% | 3 | $156 |
| Q4'25 | modeled | +$49 | 50.0% | 4 | $590 |
| Q1'26 | modeled | +$4,717 | 80.0% | 5 | $254 |
| Q2'26 live | live | +$3,778 | 57.1% | 7 | $750 |
| Q3'26 live | live | −$692 | 14.3% | 7 | $916 |
Drawdowns are EOD basis; intrabar peak-to-trough runs higher. Live quarters are real-account results at the same preset.
Stats · modeled and live, separately
| Layer | Avg win / loss | W:L | Largest win / loss | Max DD EOD | Sharpe | Sortino | Calmar | Avg bars |
|---|---|---|---|---|---|---|---|---|
| Modeled Apr 2025 – Mar 2026 | $760 / −$197 | 3.86 | $1,932 / −$590 | $1,770 (1.77%) | 1.57 | 5.90 | 3.07 | 12.4 |
| Live Apr 2026 – Sep 2026 | $1,144 / −$292 | 3.92 | $2,189 / −$750 | $916 (0.92%) | 1.29 | 3.76 | 6.74 | 34.9 |
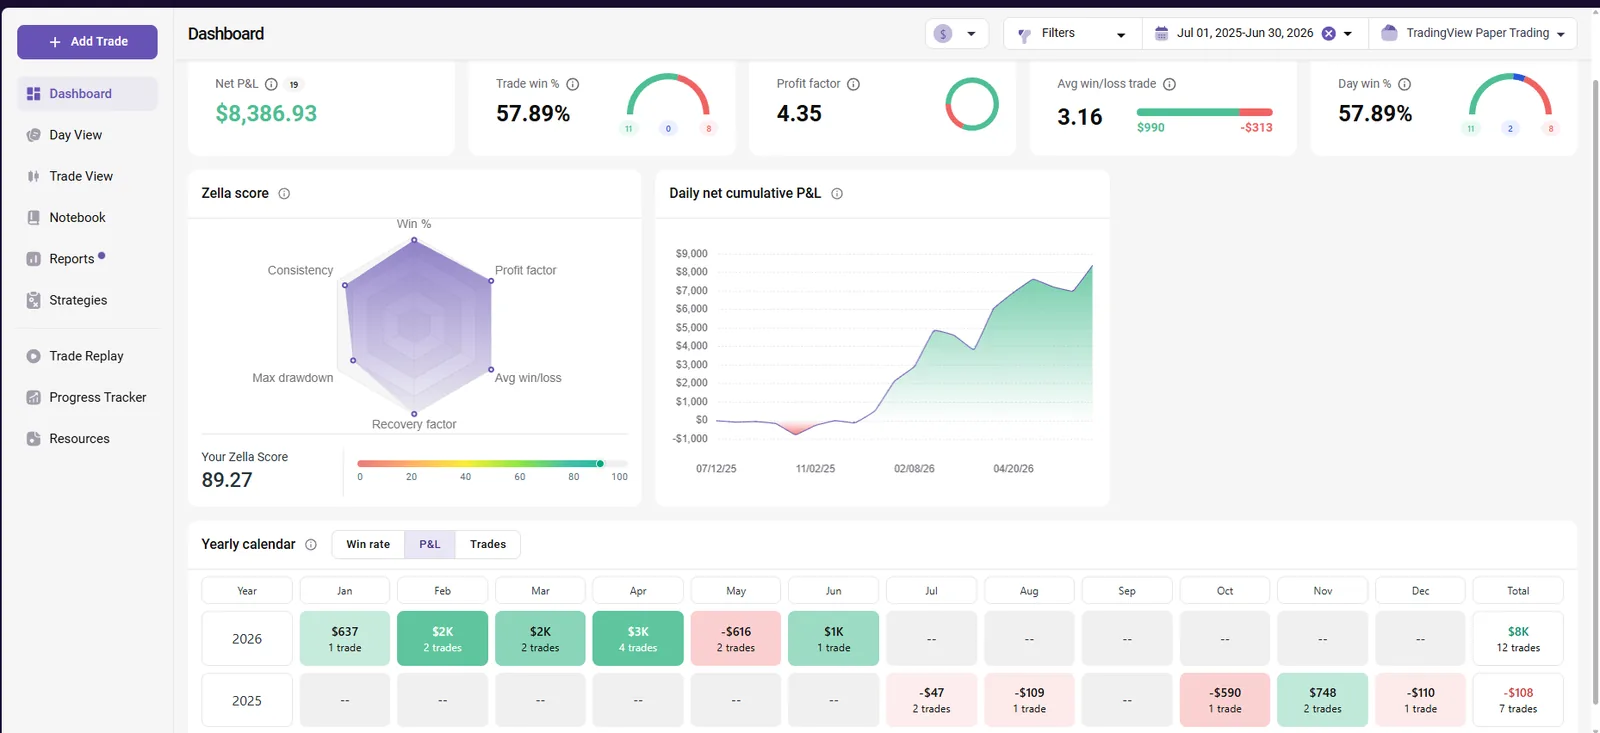
TradeZella merges partial exits into one position, so its trade count runs below the TradingView trade list; net P&L matches to the dollar.
Account sizing · Monte Carlo 1,500 paths × 3y
| Account | Qty | Blow/y | Net/y P50 (MC) | Median TTP | Status |
|---|---|---|---|---|---|
| 50K Swing | 0.15 lot | 0.00% | $1,935 | 494d | SAFE |
| 100K Swing | 0.30 lot | 0.00% | $3,870 | 494d | SAFE |
| 200K Swing | 0.60 lot | 0.00% | $7,740 | 494d | SAFE |
Monte Carlo, 1,500 paths, 3-year horizon, input Apr 2025 – Sep 2026. Forecast layer, separate from modeled and live results above. Drawdown floor: static; swing account, positions may be held overnight.
Risk disclosure
Modeled Apr 2025 – Mar 2026 plus live Apr 2026 – Sep 2026 at the stated presets. Past performance, modeled or live, does not guarantee future results. Futures and CFD trading involves substantial risk of loss; prop-firm accounts add breach rules (daily/EOD drawdown) that can terminate an account regardless of long-term edge. Size accordingly.
How Gap works
Gap trades the weekly gap — the price dislocation between Friday's close and Sunday's open. When markets reopen, that gap becomes a magnet and a battleground: price either travels back to fill it, or rejects it and continues away. Gap is built to capture both behaviours with strict, pre-defined entry conditions.
Because a tradeable gap only forms under specific conditions, signals are sparse by design. That selectivity is where the edge concentrates. The exact qualification filters, entry triggers and exit logic are proprietary and hardcoded in the script.
Gap runs on MNQ, MGC, NAS and XAU. On futures it is sized for EOD Trailing prop accounts; on forex it runs on Forex Swing accounts. Gap trades rarely, but in the Precision portfolios it is the main driver of risk — a core component of those portfolios.
How these numbers were calculated
Trade counts, win rates, profit factors, drawdown values come directly from TradingView Strategy Tester for the baseline preset shown. Verify by running the strategy in your own TradingView after purchase — numbers match 1:1.
DD%, SL%, payout potential : blow ratio and percentile breakdowns are computed from the same trade list using industry-standard methodology. Anyone with the raw trade list can reproduce these in Excel or Python.
Time-to-payout, Pay/y, Net $/y, Blow rate, and Viability in the sizing table come from a 1,500-path Monte Carlo v6 simulation over a 3-year horizon. Block bootstrap (5-day blocks) preserves serial autocorrelation of trade streaks.
Get Gap + 9 more strategies.
Gap ships in every tier — Single Bundle, Track Combo and Ultimate — together with Open, Trace, Hook, Anchor, Pivot and Reject. TradingView invite access, sizing presets for every prop tier, monthly updates.
Get the closed trades by email, updated twice a week.
This month’s closed trades, newest first, grouped by day, with the total per portfolio — updated twice a week. Plus the Playbook.
By email, from Puerto Viejo, Costa Rica. Unsubscribe anytime.