Squeeze
Volatility Squeeze
Squeeze waits for a period of clearly compressed volatility and trades its release. The range it trades is defined by volatility itself, not by a fixed time window. Runs on MNQ, MGC, NAS and XAU. Total +$62,622 across all tracks at 100K presets (Apr 2025 – Oct 2026): modeled +$4,077, live +$58,545; best PF 1.99 (XAU).
At a glance
1.99 best PF (XAU) · 56.9% best WR (XAU)
Best-performing instrument per metric (max 3 from one instrument), total Apr 2025 – Oct 2026 at the 100K preset; modeled and live layers per instrument below. Forecast metrics: Monte Carlo, 1,500 paths, 3-year horizon, input Apr 2025 – Oct 2026. Viability 3y = % of MC paths that never hit the hard drawdown. Payout potential : blow = full payout units reached in profit per one account blow over 3y (potential, not a payout schedule). TTP = median days to first payout unit.
Take Squeeze’s numbers with you.
The Playbook puts Squeeze next to every other strategy and portfolio in the catalogue, modeled and live shown separately, with the preset for each account tier. One PDF, then our letters with what the systems did.
By email, from Puerto Viejo, Costa Rica. Unsubscribe anytime.
100K FP preset (1 ct) · portfolio-only
1.61 PF · 51.9% Win rate · $1,431 Max DD (EOD) · 1.20 Sharpe
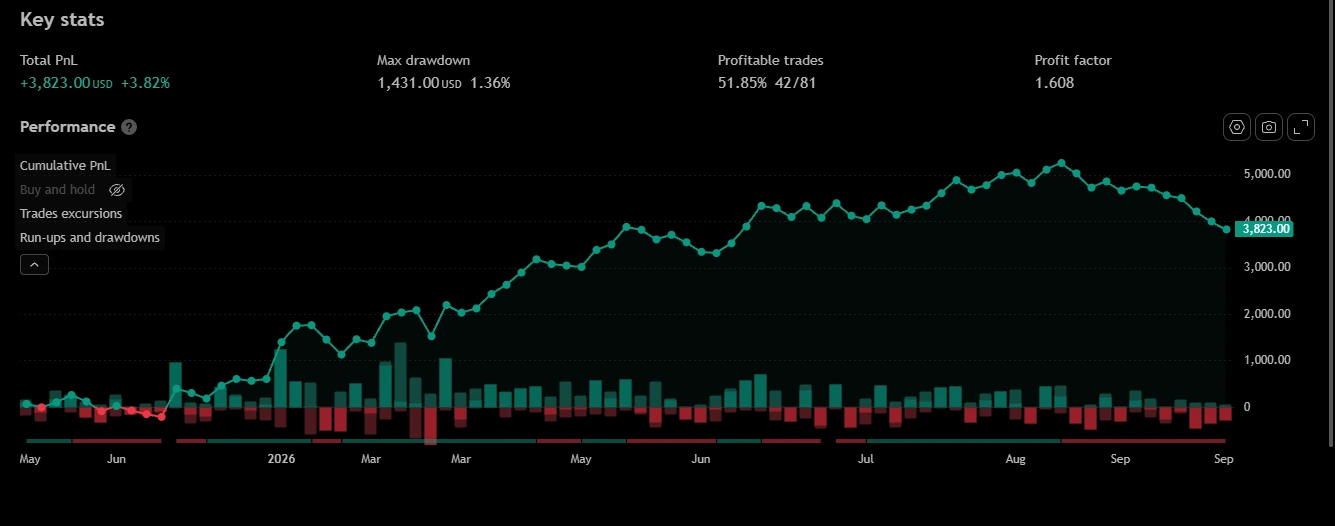
Equity curve · modeled + live
Daily P&L applied to the $100,000 starting balance at the 100K FP preset (1 ct), log scale. Gray = modeled (2025-04-01 → 2026-03-31); accent = live (2026-04-01 → 2026-10-30), right of the “LIVE →” marker.
Modeled 12 months (Apr 2025 – Mar 2026) · detail
Quarterly breakdown · modeled Q2'25–Q1'26, live since Q2'26
| Quarter | Layer | Net | WR | Trades | Max DD (EOD) |
|---|---|---|---|---|---|
| Q2'25 | modeled | −$216 | 40.0% | 10 | $473 |
| Q3'25 | modeled | +$0 | — | 0 | $0 |
| Q4'25 | modeled | +$817 | 57.1% | 7 | $212 |
| Q1'26 | modeled | +$1,429 | 61.5% | 13 | $633 |
| Q2'26 live | live | +$2,089 | 53.8% | 26 | $565 |
| Q3'26 live | live | −$296 | 48.0% | 25 | $1,431 |
| Q4'26 live | live | +$0 | — | 0 | $0 |
Drawdowns are EOD basis; intrabar peak-to-trough runs higher. Live quarters are real-account results at the same preset.
Stats · modeled and live, separately
| Layer | Avg win / loss | W:L | Largest win / loss | Max DD EOD | Sharpe | Sortino | Calmar | Avg bars |
|---|---|---|---|---|---|---|---|---|
| Modeled Apr 2025 – Mar 2026 | $274 / −$168 | 1.63 | $792 / −$561 | $633 (0.63%) | 1.11 | 2.29 | 3.21 | — |
| Live Apr 2026 – Oct 2026 | $221 / −$158 | 1.40 | $446 / −$307 | $1,431 (1.26%) | 1.35 | 2.25 | 2.15 | — |
Account sizing · Monte Carlo 1,500 paths × 3y
| Account | Qty | Blow/y | Net/y P50 (MC) | Median TTP | Status |
|---|---|---|---|---|---|
| 50K FP | 1 ct | 2.79% | $1,635 | 328d | SAFE |
| 100K FP | 1 ct | 0.54% | $1,635 | 756d | SAFE |
| 150K FP | 2 ct | 2.09% | $3,269 | 501d | SAFE |
Monte Carlo, 1,500 paths, 3-year horizon, input Apr 2025 – Oct 2026. Forecast layer, separate from modeled and live results above. Drawdown floor: end-of-day trailing.
100K FP preset (2 ct) · portfolio-only
1.39 PF · 40.4% Win rate · $4,970 Max DD (EOD) · 1.33 Sharpe
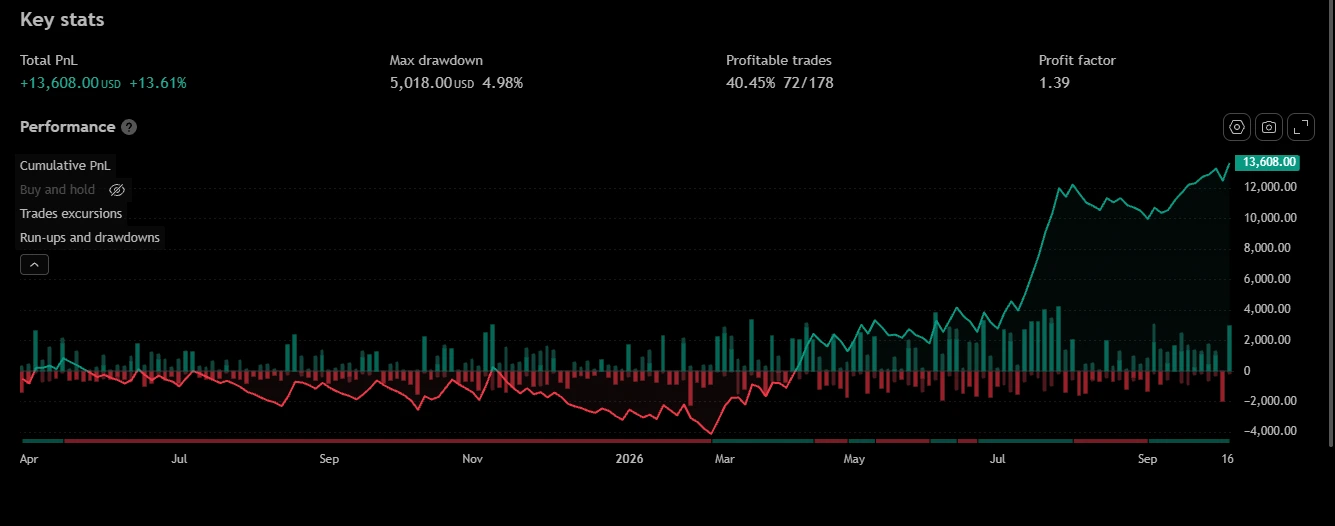
Equity curve · modeled + live
Daily P&L applied to the $100,000 starting balance at the 100K FP preset (2 ct), log scale. Gray = modeled (2025-04-01 → 2026-03-31); accent = live (2026-04-01 → 2026-10-30), right of the “LIVE →” marker.
Modeled 12 months (Apr 2025 – Mar 2026) · detail
Quarterly breakdown · modeled Q2'25–Q1'26, live since Q2'26
| Quarter | Layer | Net | WR | Trades | Max DD (EOD) |
|---|---|---|---|---|---|
| Q2'25 | modeled | −$723 | 34.8% | 23 | $1,531 |
| Q3'25 | modeled | −$234 | 29.0% | 31 | $2,311 |
| Q4'25 | modeled | −$2,276 | 28.6% | 35 | $3,462 |
| Q1'26 | modeled | +$2,317 | 47.4% | 19 | $1,931 |
| Q2'26 live | live | +$4,060 | 42.9% | 35 | $1,605 |
| Q3'26 live | live | +$8,518 | 53.6% | 28 | $2,255 |
| Q4'26 live | live | +$1,946 | 85.7% | 7 | $786 |
Drawdowns are EOD basis; intrabar peak-to-trough runs higher. Live quarters are real-account results at the same preset.
Stats · modeled and live, separately
| Layer | Avg win / loss | W:L | Largest win / loss | Max DD EOD | Sharpe | Sortino | Calmar | Avg bars |
|---|---|---|---|---|---|---|---|---|
| Modeled Apr 2025 – Mar 2026 | $533 / −$279 | 1.91 | $1,322 / −$882 | $4,970 (4.97%) | -0.19 | -0.33 | -0.18 | — |
| Live Apr 2026 – Oct 2026 | $813 / −$434 | 1.87 | $1,652 / −$786 | $2,255 (2.26%) | 2.91 | 6.03 | 11.04 | — |
Account sizing · Monte Carlo 1,500 paths × 3y
| Account | Qty | Blow/y | Net/y P50 (MC) | Median TTP | Status |
|---|---|---|---|---|---|
| 50K FP | 1 ct | 8.85% | $3,028 | 168d | SAFE |
| 100K FP | 2 ct | 13.79% | $6,056 | 168d | SAFE |
| 150K FP | 3 ct | 13.70% | $9,083 | 168d | SAFE |
Monte Carlo, 1,500 paths, 3-year horizon, input Apr 2025 – Oct 2026. Forecast layer, separate from modeled and live results above. Drawdown floor: end-of-day trailing.
100K Swing preset (7 lot) · portfolio-only
1.53 PF · 39.8% Win rate · $6,817 Max DD (EOD) · 1.66 Sharpe
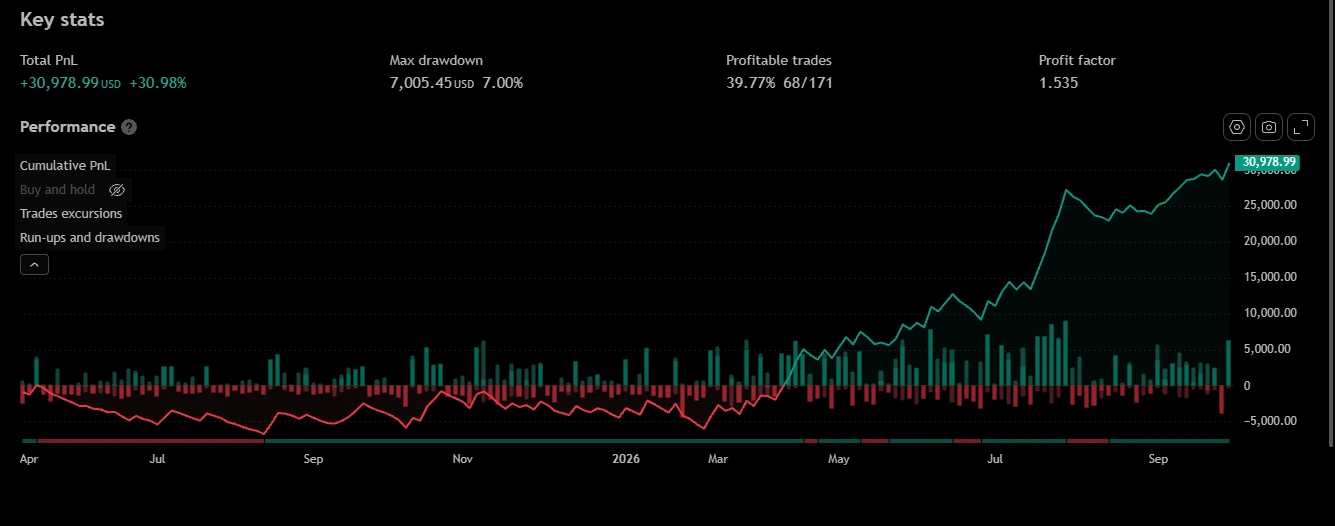
Equity curve · modeled + live
Daily P&L applied to the $100,000 starting balance at the 100K Swing preset (7 lot), log scale. Gray = modeled (2025-04-01 → 2026-03-31); accent = live (2026-04-01 → 2026-10-30), right of the “LIVE →” marker.
Modeled 12 months (Apr 2025 – Mar 2026) · detail
Quarterly breakdown · modeled Q2'25–Q1'26, live since Q2'26
| Quarter | Layer | Net | WR | Trades | Max DD (EOD) |
|---|---|---|---|---|---|
| Q2'25 | modeled | −$4,912 | 15.8% | 19 | $4,966 |
| Q3'25 | modeled | +$1,868 | 32.3% | 31 | $3,256 |
| Q4'25 | modeled | −$1,440 | 31.4% | 35 | $3,690 |
| Q1'26 | modeled | +$2,335 | 38.9% | 18 | $3,890 |
| Q2'26 live | live | +$13,905 | 50.0% | 34 | $3,599 |
| Q3'26 live | live | +$15,832 | 55.6% | 27 | $3,795 |
| Q4'26 live | live | +$3,391 | 71.4% | 7 | $1,387 |
Drawdowns are EOD basis; intrabar peak-to-trough runs higher. Live quarters are real-account results at the same preset.
Stats · modeled and live, separately
| Layer | Avg win / loss | W:L | Largest win / loss | Max DD EOD | Sharpe | Sortino | Calmar | Avg bars |
|---|---|---|---|---|---|---|---|---|
| Modeled Apr 2025 – Mar 2026 | $1,063 / −$488 | 2.18 | $1,965 / −$1,630 | $6,817 (6.82%) | -0.25 | -0.44 | -0.32 | — |
| Live Apr 2026 – Oct 2026 | $1,513 / −$737 | 2.05 | $3,301 / −$1,387 | $3,795 (3.80%) | 3.61 | 8.45 | 14.96 | — |
Account sizing · Monte Carlo 1,500 paths × 3y
| Account | Qty | Blow/y | Net/y P50 (MC) | Median TTP | Status |
|---|---|---|---|---|---|
| 50K Swing | 3.5 lot | 0.38% | $6,818 | 128d | SAFE |
| 100K Swing | 7 lot | 0.38% | $13,636 | 128d | SAFE |
| 200K Swing | 14 lot | 0.38% | $27,271 | 128d | SAFE |
Monte Carlo, 1,500 paths, 3-year horizon, input Apr 2025 – Oct 2026. Forecast layer, separate from modeled and live results above. Drawdown floor: static; swing account, positions may be held overnight.
100K Swing preset (0.30 lot) · portfolio-only
1.99 PF · 56.9% Win rate · $2,979 Max DD (EOD) · 1.65 Sharpe
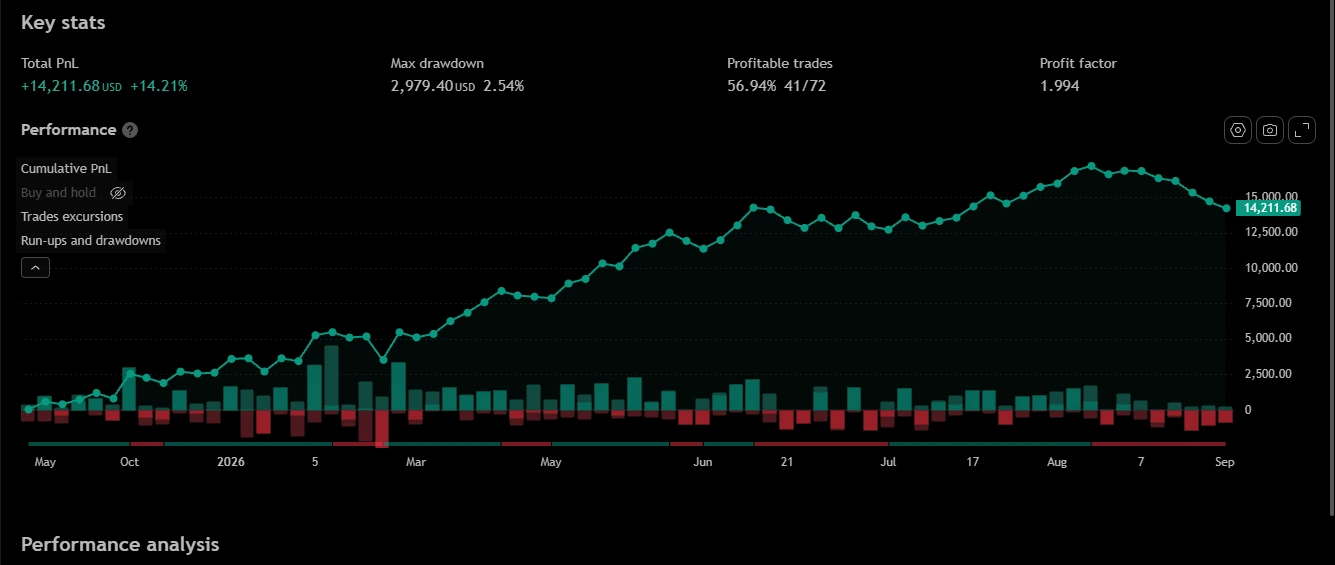
Equity curve · modeled + live
Daily P&L applied to the $100,000 starting balance at the 100K Swing preset (0.30 lot), log scale. Gray = modeled (2025-04-01 → 2026-03-31); accent = live (2026-04-01 → 2026-10-30), right of the “LIVE →” marker.
Modeled 12 months (Apr 2025 – Mar 2026) · detail
Quarterly breakdown · modeled Q2'25–Q1'26, live since Q2'26
| Quarter | Layer | Net | WR | Trades | Max DD (EOD) |
|---|---|---|---|---|---|
| Q2'25 | modeled | +$803 | 66.7% | 6 | $390 |
| Q3'25 | modeled | +$0 | — | 0 | $0 |
| Q4'25 | modeled | +$1,819 | 50.0% | 6 | $650 |
| Q1'26 | modeled | +$2,489 | 58.3% | 12 | $1,947 |
| Q2'26 live | live | +$7,822 | 59.3% | 27 | $1,447 |
| Q3'26 live | live | +$1,277 | 52.4% | 21 | $2,979 |
| Q4'26 live | live | +$0 | — | 0 | $0 |
Drawdowns are EOD basis; intrabar peak-to-trough runs higher. Live quarters are real-account results at the same preset.
Stats · modeled and live, separately
| Layer | Avg win / loss | W:L | Largest win / loss | Max DD EOD | Sharpe | Sortino | Calmar | Avg bars |
|---|---|---|---|---|---|---|---|---|
| Modeled Apr 2025 – Mar 2026 | $713 / −$487 | 1.46 | $1,940 / −$1,645 | $1,947 (1.95%) | 1.12 | 2.26 | 2.63 | — |
| Live Apr 2026 – Oct 2026 | $686 / −$449 | 1.53 | $1,306 / −$825 | $2,979 (2.50%) | 2.33 | 4.35 | 5.24 | — |
Account sizing · Monte Carlo 1,500 paths × 3y
| Account | Qty | Blow/y | Net/y P50 (MC) | Median TTP | Status |
|---|---|---|---|---|---|
| 50K Swing | 0.15 lot | 0.00% | $3,042 | 310d | SAFE |
| 100K Swing | 0.30 lot | 0.00% | $6,083 | 310d | SAFE |
| 200K Swing | 0.60 lot | 0.00% | $12,167 | 310d | SAFE |
Monte Carlo, 1,500 paths, 3-year horizon, input Apr 2025 – Oct 2026. Forecast layer, separate from modeled and live results above. Drawdown floor: static; swing account, positions may be held overnight.
Risk disclosure
Modeled Apr 2025 – Mar 2026 plus live Apr 2026 – Oct 2026 at the stated presets. Past performance, modeled or live, does not guarantee future results. Futures and CFD trading involves substantial risk of loss; prop-firm accounts add breach rules (daily/EOD drawdown) that can terminate an account regardless of long-term edge. Size accordingly.
How Squeeze works
After a period of clearly compressed volatility, a market usually leaves its range with a sharp move. Squeeze waits for that compression and trades the release, in the direction the move continues. The exact qualification filters, entry triggers and exit logic are proprietary and hardcoded in the script.
Where Open trades the range built in a fixed window after the open, Squeeze trades a range defined by volatility itself.
Squeeze is selective by design: no compression, no trade. Every entry uses a fixed preset with no mechanism to add to a position, and holds are short, within the session. On the futures presets (MNQ, MGC) the EOD guard closes any open position before the session ends.
How these numbers were calculated
Trade counts, win rates, profit factors, drawdown values come directly from TradingView Strategy Tester for the baseline preset. Verify by running the strategy in your own TradingView after purchase — numbers match 1:1.
DD%, SL%, payout potential : blow ratio and percentile breakdowns are computed from the same trade list using industry-standard methodology. Reproducible in Excel or Python.
Time-to-payout, payout potential, Net $/y, blow rate and viability come from a 1,500-path Monte Carlo simulation over a 3-year horizon (input Apr 2025 – Sep 2026). Block bootstrap (5-day blocks) preserves serial autocorrelation of trade streaks.
Get Squeeze + 11 more strategies.
Every Puravida Edge plan includes all 11 strategies and ongoing updates. Every Lifetime tier can be paid in 12 monthly instalments — full access from the first payment.
Quarter by quarter, modeled next to live: Modeled vs live results by strategy →
Get the closed trades by email, updated twice a week.
This month’s closed trades, newest first, grouped by day, with the total per portfolio — updated twice a week. Plus the Playbook.
By email, from Puerto Viejo, Costa Rica. Unsubscribe anytime.