Fewer strategies, more per dollar of drawdown: same 32 strategies, two prop accounts
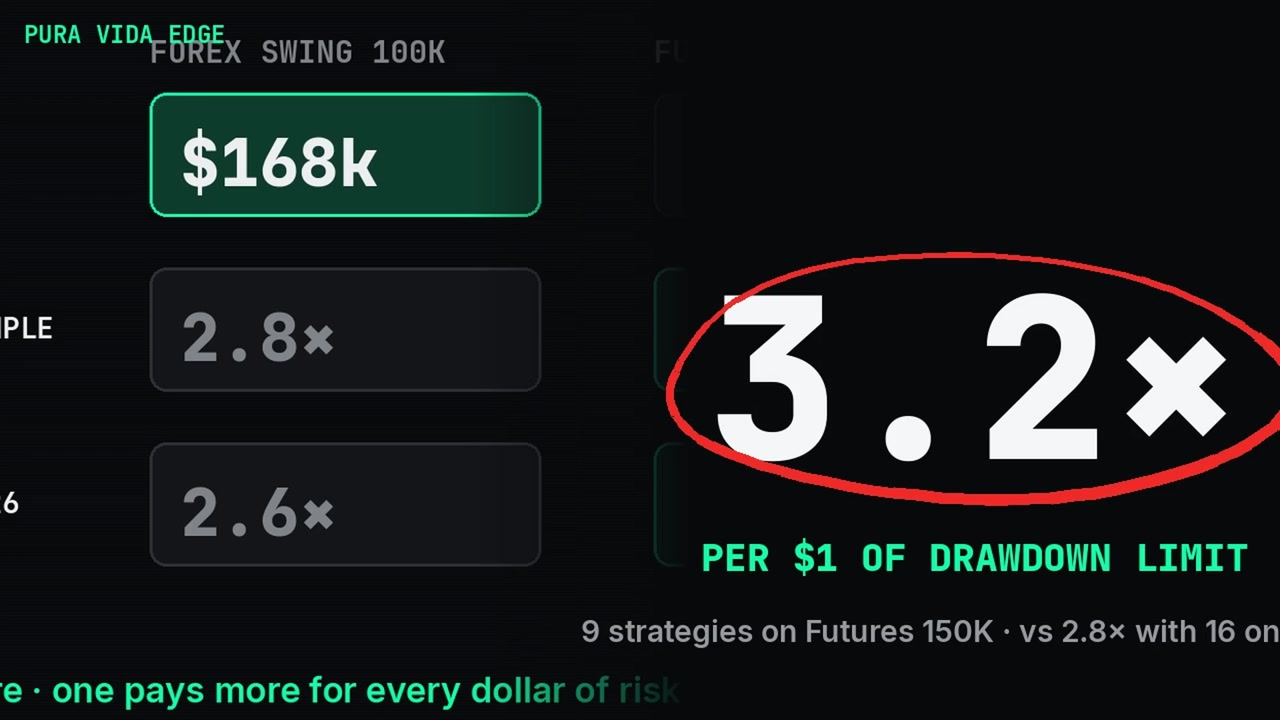
Nine strategies on a Futures 150K account earned 3.2× per dollar of drawdown limit in-sample and 3.6× in Q3 2026; sixteen on a Forex Swing 100K earned 2.8× and 2.6×. In dollars, Forex won: $168k against $87k in-sample (source: PV_EDGE Master Data, DATA 2026-10-10, catalog only).
Video page with full transcript →
Why do the same strategies fit differently on two accounts?
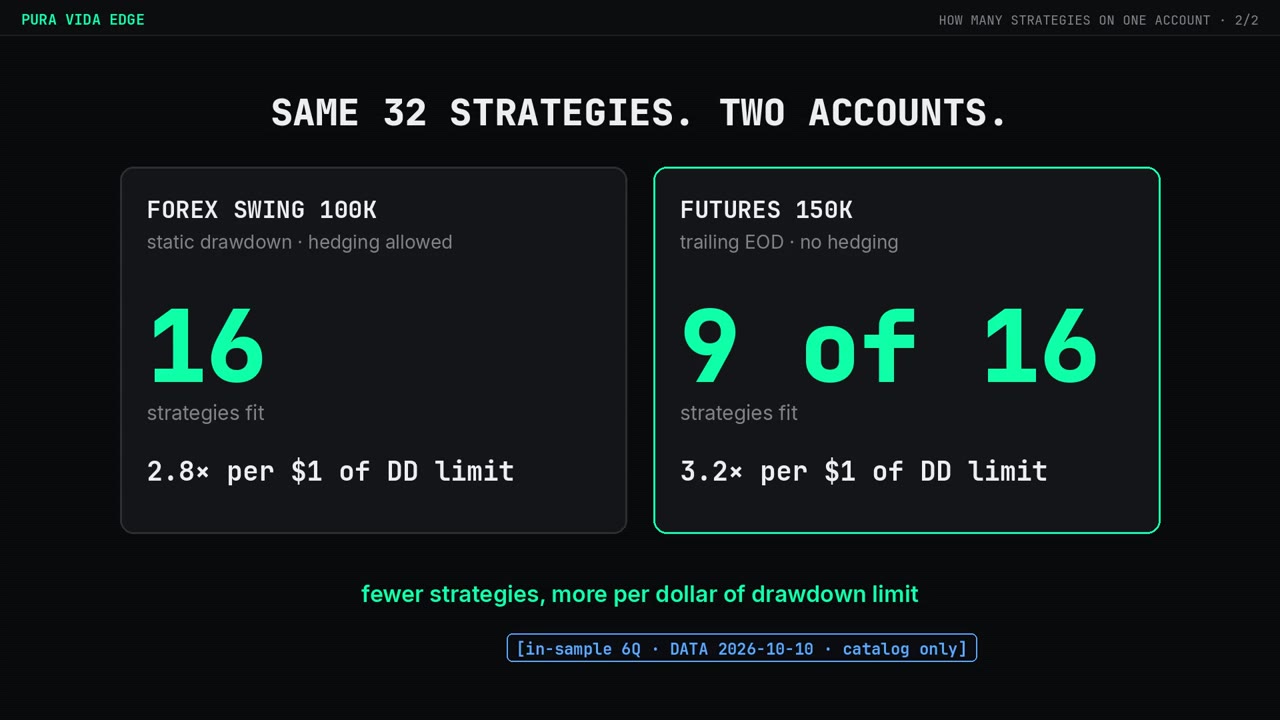
Two rules. A static floor never moves; a trailing floor follows your peak until the buffer locks, and every strategy is sized to that floor, so the trailing account fits less. And no hedging means two strategies can't hold opposite positions on one instrument, so one of them has to go. On Futures 150K that stops at nine of sixteen.
What did each account earn?
| Forex Swing 100K | Futures 150K | |
|---|---|---|
| Rules | static drawdown, hedging allowed | trailing EOD, no hedging |
| Strategies that fit | 16 | 9 of 16 |
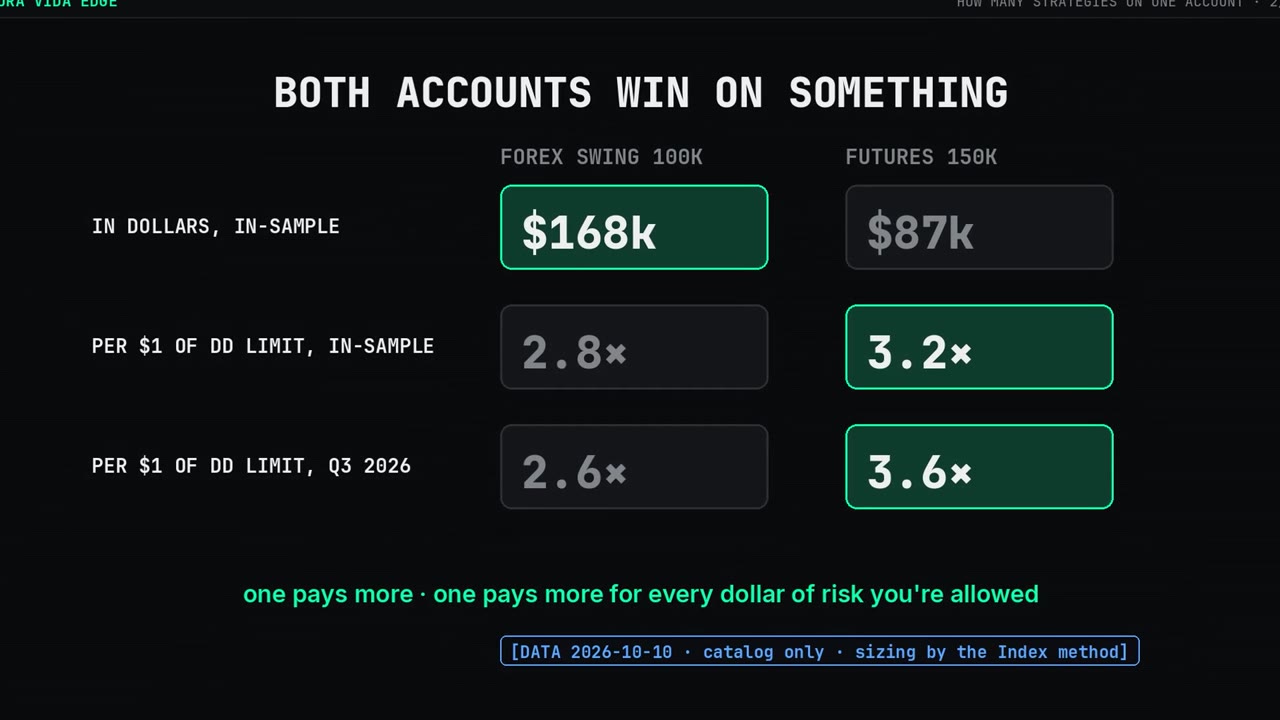
| In dollars, in-sample | $168k | $87k |
| Per $1 of DD limit, in-sample | 2.8× | 3.2× |
| Per $1 of DD limit, Q3 2026 | 2.6× | 3.6× |
Which account is better?
Both win on something. Forex pays more. Futures pays more for every dollar of risk you're allowed. Which one is better depends on which number your account runs out of first. The no-hedging rule removed collisions, not the worst tracks; above half the list every remaining candidate overlapped something already in the basket.
What does each look like on a prop account?
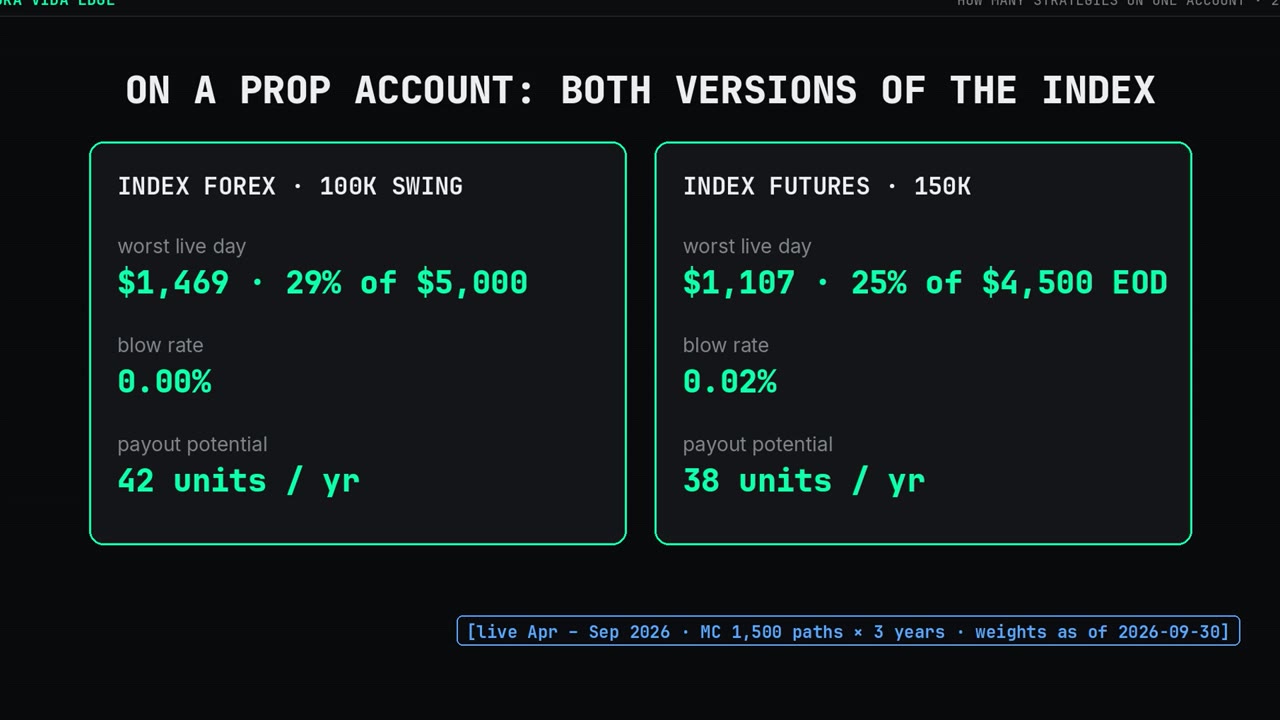
Both versions of the PVE Index tell the same story. Forex: worst live day $1,469 against a $5,000 daily limit, blow rate 0.00%, 42 payout units a year. Futures: worst live day $1,107 against a $4,500 trailing floor, 0.02%, 38 units a year. How a trailing floor moves is in trailing vs static vs daily loss drawdown.
The rule is the filter. The Playbook shows what fits through it.
Which configurations fit tight daily limits, trailing floors and consistency rules — sized to the drawdown, not the balance. One PDF, then our letters with what the systems did.
By email, from Puerto Viejo, Costa Rica. Unsubscribe anytime.
Related
FAQ
Why are futures shares lumpier? Because one contract is the smallest step. A quiet track still rounds up to one contract; on forex a track can be sized to a fraction of a lot.
Does "nine fit" mean the other seven are worse? No. They collided with tracks already in the basket under the no-hedging rule. On the Forex version all sixteen run together.
Is 3.2× a return? It's net over the window divided by the account's drawdown limit, a comparison of baskets per unit of allowed risk, not an annual return.
Modeled and live layers are labeled separately. Monte Carlo figures (1,500 paths × 3 years) are a forecast. Hypothetical performance; past results do not guarantee future returns. Not financial advice.